The Great Infrastructure Exodus: How Mid-Market Firms Are Leaving Legacy Technology Behind in 2025
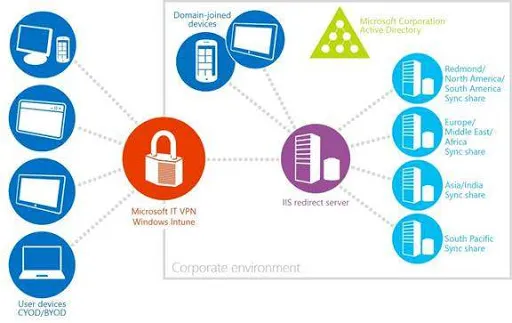
Photo: Enterprise data management, CC BY-SA 2.0, via Wikimedia Commons
For years, legacy systems occupied an uncomfortable but familiar position in the mid-market: too embedded to replace easily, too costly to maintain indefinitely, and too limiting to support the growth ambitions of companies that had outpaced them. In 2025, that uneasy equilibrium has broken. The pace of legacy system abandonment among US mid-market firms—generally defined as companies generating between $10 million and $1 billion in annual revenue—has accelerated sharply, driven by a convergence of financial, operational, and competitive pressures that have made the status quo untenable.
This analysis explores the forces behind that acceleration, the platforms capturing market share, and the practical considerations that should inform any modernization decision.
Why the Tipping Point Arrived Now
The reluctance to retire legacy systems has historically been rational, if shortsighted. Replacement projects are expensive, disruptive, and fraught with implementation risk. Many mid-market organizations spent the better part of the 2010s patching and extending systems that were architecturally obsolete, reasoning that the cost of replacement outweighed the cost of continuation.
Several developments have fundamentally altered that calculus.
Maintenance costs have become unsustainable. Proprietary legacy platforms—particularly those built on aging ERP frameworks or custom-coded databases—require increasingly specialized talent to maintain. As the workforce of developers and administrators who built those systems has aged out or moved on, organizations have found themselves paying substantial premiums for contractors with niche expertise in technologies that the broader market has largely abandoned. For many mid-market CFOs, the total cost of ownership analysis that once justified retention now argues compellingly for replacement.
Integration demands have outpaced legacy capabilities. The modern enterprise technology stack is deeply interconnected. E-commerce platforms, customer relationship management systems, supply chain tools, and workforce management applications are expected to share data in real time. Legacy systems, designed in an era of batch processing and siloed data structures, cannot fulfill these integration requirements without expensive middleware solutions that introduce their own fragility and maintenance burden.
Cybersecurity exposure has become a board-level concern. Older systems frequently lack the security architecture necessary to defend against contemporary threat vectors. In regulated industries—financial services, healthcare, manufacturing—the compliance implications of operating on unsupported or under-secured infrastructure have escalated from operational nuisance to existential risk. Following several high-profile breaches tied to legacy vulnerability exploitation, boards and audit committees are applying direct pressure on executive teams to accelerate modernization timelines.
What Mid-Market Companies Are Choosing Instead
The replacement landscape is not monolithic. Different organizational profiles, industry verticals, and growth trajectories are driving distinct technology choices. However, several categories of solutions are capturing disproportionate adoption among mid-market firms making the transition in 2025.
Cloud-native ERP platforms. Solutions from vendors including NetSuite, Microsoft Dynamics 365, and SAP's mid-market-oriented offerings have seen substantial uptake among companies migrating off on-premises ERP systems. The appeal is multifaceted: subscription-based pricing models convert large capital expenditures into predictable operating costs, cloud hosting eliminates the infrastructure management burden, and regular vendor-managed updates ensure that organizations remain current without undertaking discrete upgrade projects.
Composable architecture and best-of-breed ecosystems. A meaningful segment of the mid-market is moving away from the monolithic suite model entirely, opting instead for composable architectures that assemble best-in-class point solutions connected through robust API frameworks. This approach offers greater flexibility and allows organizations to adopt specialized tools—advanced analytics platforms, industry-specific workflow automation, AI-powered forecasting—without being constrained by the capabilities of a single vendor's suite.
Vertical SaaS platforms. Increasingly, mid-market firms in sectors such as construction, distribution, professional services, and specialty retail are finding that purpose-built vertical SaaS solutions outperform horizontal platforms on the specific workflows that matter most to their operations. These platforms typically offer faster time-to-value and require less customization than general-purpose alternatives, reducing implementation risk considerably.
The Implementation Reality: Challenges That Demand Honest Assessment
The technology migration narrative is often told through the lens of successful outcomes. A complete analysis requires equal attention to the implementation challenges that derail or delay projects—and that drive costs well beyond initial projections.
Data migration complexity is routinely underestimated. Legacy systems frequently contain years or decades of data in formats that do not map cleanly to modern platforms. Data cleansing, normalization, and validation consume significant time and resources. Organizations that treat data migration as a technical task rather than a strategic initiative—one that requires business stakeholder engagement to resolve definitional inconsistencies and prioritize data integrity—consistently encounter costly delays.
Change management is the variable most often neglected. Technology implementations fail far more frequently due to adoption challenges than to technical deficiencies. Mid-market organizations, which often lack the dedicated change management infrastructure of large enterprises, must be intentional about communication, training, and the management of workforce anxiety that accompanies significant operational transitions.
Vendor selection requires rigorous due diligence. The mid-market technology vendor landscape includes a wide spectrum of providers, from established global platforms to emerging niche players. Evaluating financial stability, implementation partner ecosystems, customer support quality, and long-term product roadmap alignment is essential. Reference checks with companies of comparable size and complexity—not just the marquee case studies featured in vendor marketing materials—provide the most reliable signal.
Measuring Success: Metrics That Matter
Organizations that approach modernization with clearly defined success metrics are substantially more likely to achieve satisfactory outcomes than those that treat go-live as the primary milestone. Leading mid-market firms are establishing baseline measurements before migration and tracking a defined set of post-implementation indicators, including:
- Total cost of ownership reduction over a rolling 36-month window, accounting for licensing, infrastructure, support, and internal administration costs
- System integration latency, measuring the time required for data to propagate across interconnected platforms
- User adoption rates, tracked at the departmental level to identify pockets of resistance that require targeted intervention
- Process cycle time improvements in key operational workflows, such as order-to-cash, procure-to-pay, and financial close
Organizations that establish these baselines and review them at regular intervals are better positioned to course-correct when implementation trajectories deviate from plan—and to demonstrate concrete return on investment to board members and investors who scrutinize technology capital allocation.
The Strategic Imperative
The mid-market firms that emerge from this technology transition cycle in the strongest competitive position will not necessarily be those that moved fastest. They will be those that moved most deliberately—selecting solutions aligned with their specific operational requirements, executing migrations with appropriate investment in change management and data integrity, and establishing governance frameworks that position their new platforms for long-term scalability.
For business leaders currently evaluating modernization pathways, the central question is not whether to act, but how to act with sufficient rigor to protect the investment and realize the anticipated value. The legacy era is closing. The architecture decisions being made today will define organizational capability for the decade ahead.
PG168 Enterprise is committed to providing the analysis and frameworks that help enterprise leaders navigate these decisions with confidence and clarity.